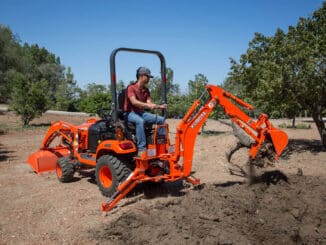
Kubota insurance is a specialist way to protect a Kubota tractor, mower or construction machine against damage, theft and other risks, alongside (not instead of) a standard warranty and any farm or home policy you already have.
It typically comes via Kubota‑endorsed property damage cover (often through KTAC) and optional extended warranty such as the Orange Protection Program.
What Kubota Insurance is
Kubota‑endorsed property damage insurance is a policy designed specifically for Kubota equipment, arranged through Kubota Tractor Acceptance Corporation (KTAC) and underwritten by insurers such as Ohio Indemnity Company in the US. It protects the machine itself against a broad range of physical damage risks, on and off your property, including during transport.
This coverage is separate from liability insurance (injuries or third‑party damage) and from your standard homeowners or farm policy, which often exclude or restrict cover for mobile agricultural and construction equipment. In many cases, Kubota’s own finance arm requires proof of suitable equipment insurance if the machine is financed, and the KTAC policy is built to meet that requirement.
Key Kubota insurance options
For most owners there are two main Kubota‑branded products to understand.
-
Kubota‑endorsed property damage (KTAC) – covers accidental physical damage and loss to the unit (e.g. theft, fire, rollover, collision, flood) with a fixed deductible and replacement‑cost provisions.
-
Orange Protection Program – Kubota’s extended warranty that lengthens the period during which Kubota pays to fix defects in materials or workmanship beyond the standard limited warranty.
These can be combined: the property damage policy handles accidents and perils, while the extended warranty handles failures caused by manufacturing defects after the normal warranty ends. Many dealers present them together at the point of sale and can also finance the premiums into your equipment loan.
What Kubota Insurance‑endorsed property damage covers
Kubota‑endorsed property damage insurance is an “all‑risk” style policy targeted at the real‑world hazards Kubota owners face. Typical covered causes of loss include:
-
Theft and attempted theft of the machine.
-
Fire, including barn or building fires.
-
Collision and rollover/upset, whether on your property or elsewhere, often including transport incidents on a trailer.
-
Falling objects, such as tree limbs or debris.
-
Weather‑related perils like hail, tornado, hurricane and flood.
-
Vandalism and malicious damage; many policies also extend to infestation damage after Kubota removed “infestation” as a standard exclusion in 2018.
Policies are usually written with a fixed deductible (commonly around 250 USD per claim) and may include a “replacement option”, where a total loss in the first 60 months of the finance term can trigger replacement with new Kubota equipment of like kind and quality up to the original sales price, including taxes and fees. Coverage generally applies regardless of where the machine is used or who is operating it, subject to the policy terms.
What Kubota insurance does not cover
Even though it is broad, Kubota‑endorsed property damage insurance is not a maintenance plan. Common exclusions include:
-
Mechanical breakdowns, internal failures and normal wear and tear (for example, a seal failing without an accident, or an electrical fault in a valve).
-
Tyres, tracks, bucket teeth and cutting edges, which are treated as wear items, especially under extended warranty programs.
-
Fraudulent claims, government seizure, nuclear events, war and terrorism.
-
Any loss outside the policy period or beyond specified hour limitations on some extended warranty coverages.
Owners sometimes expect minor leaks, routine hydraulic issues or non‑accidental component failures to be covered, but in practice those are treated as service/warranty questions, not insurance claims.
It is also important to remember that liability for injuries or third‑party property damage is a different policy type and is not automatically included in the Kubota‑endorsed property damage cover.
How KTAC (Kubota Insurance) differs from homeowners or farm insurance
Many people ask why they need KTAC if they already have a homeowners or farm policy. The main differences are in scope, portability and settlement terms.
Coverage differences table
Because of these differences, many Kubota dealers recommend KTAC even for units that never leave the farm, particularly when homeowners insurers will not properly schedule or value the machine.
In finance scenarios, Kubota Credit may insist on proof of equivalent coverage if you choose not to use KTAC.
Kubota Insurance – Orange Protection Extended Warranty
The Orange Protection Program is Kubota’s own extended warranty that prolongs coverage for defects in materials or workmanship after the standard warranty expires. It can extend both basic and powertrain coverage by one or two additional years depending on the model and application, often up to thousands of engine or powertrain hours.
Benefits highlighted by Kubota include comprehensive coverage on the same terms as the limited warranty, no deductibles, the use of genuine Kubota parts, and full transferability if you sell the machine during the coverage period.
The program can normally be purchased with the equipment or any time before the original basic warranty expires, and it may be financed with the tractor or implement.
Term vs annual Kubota Insurance policies
Kubota‑endorsed property damage can be structured either as a term policy tied to your finance agreement or as an annual policy.
-
Term policy: Matches the Kubota Credit retail contract, with a locked‑in rate for the term, premium often rolled into the monthly finance payment, and a replacement option for total loss during the first 60 months if the contract exceeds that term.
-
Annual policy: Available for customers who paid cash or after the finance agreement is paid off, with yearly renewals while you own the machine.
Both variants usually carry the same basic deductible and all‑risk coverage structure, but the term policy is particularly attractive for new financed machines because it simultaneously satisfies the lender’s requirement and simplifies budgeting.
Kubota Insurance – Typical costs and value
Kubota dealers often quote KTAC premiums as a modest monthly figure when financed, depending on machine value, state and term length. Owners on discussion forums describe costs around a few tens of dollars per month for compact tractors and RTVs, comparing it with what auto insurers or farm policies would charge for similar physical damage cover.
From a value perspective, the replacement‑cost feature, low deductible and broad off‑property coverage can easily outweigh several years of premium if you suffer a serious theft, rollover or flood event.
Many users also report straightforward claims experiences, where significant damage or total losses were settled quickly and the machine repaired or replaced with minimal hassle.
Practical buying tips
When you order a new Kubota, the sales process is the ideal time to decide how you will insure it. Steps owners commonly take include:
-
Asking the dealer for a written summary of KTAC coverage, deductible, and replacement‑cost conditions, including any hour limits or exclusions.
-
Checking with your existing insurer (home, farm, or commercial) to see whether they can schedule the tractor, what perils they cover, and whether coverage extends off‑property and during transport.
-
Comparing total cost over the life of the finance term, including differences in deductibles and settlement basis (actual cash value vs replacement cost).
If you purchase the Orange Protection extended warranty, verify exactly how many additional years and hours you get for both basic and powertrain coverage, and keep documentation with your service records.
Also make sure servicing is done in line with Kubota’s schedule, as poor maintenance can complicate or void warranty claims.
Kubota Insurance FAQs
-
What is Kubota insurance?
Kubota insurance usually refers to Kubota‑endorsed property damage coverage for tractors, mowers and construction equipment, marketed through Kubota Tractor Acceptance Corporation (KTAC) in the US. It protects the machine itself against accidental physical damage and theft, complementing rather than replacing your warranty. -
Who provides Kubota‑endorsed insurance?
Kubota‑endorsed property damage policies are arranged by KTAC Insurance Agency and underwritten by insurers such as Ohio Indemnity Company for eligible US residents. KTAC is closely linked to Kubota’s finance operations, which is why it integrates neatly with Kubota Credit contracts. -
Is Kubota insurance the same as a warranty?
No, insurance and warranty are different tools: warranty (including the Orange Protection Program) covers defects in materials or workmanship, while insurance covers accidents and outside perils such as fire, theft or collision. Insurance does not pay for wear and tear, routine breakdowns or maintenance items. -
What does KTAC insurance typically cover?
KTAC’s Kubota‑endorsed policies include coverage for theft, fire, glass breakage, collision, rollover, falling objects, hail, tornado, hurricane, flood, vandalism and other accidental physical damage, plus some causes like infestation following policy changes. Coverage applies on your property, away from it and during transportation of the machine. -
What is the usual deductible on Kubota‑endorsed policies?
The Kubota‑endorsed property damage brochure highlights a low fixed deductible, commonly around 250 USD per occurrence, designed to keep out‑of‑pocket costs manageable for owners. This contrasts with many homeowners policies that use much higher deductibles for property claims. -
Does Kubota insurance cover my tractor if I roll it over?
Yes, rollover or upset is specifically listed as a covered cause of loss in KTAC marketing materials, meaning repairs or total loss settlements would be handled subject to policy terms and deductible. This is one of the main reasons compact tractor owners choose the Kubota‑endorsed cover rather than relying solely on home insurance. -
Is my Kubota covered while on a trailer or used off my property?
Kubota‑endorsed property damage insurance is promoted as covering your equipment “on and off your property” and “transportation included”, meaning it responds when the machine is being hauled or used away from home. Many homeowners policies do not offer this kind of portable coverage by default. -
Does Kubota insurance cover mechanical breakdown?
No, mechanical breakdown, normal wear and tear and maintenance issues are excluded; owners discussing claims note that leaking cylinders or non‑functional valves with no accident involved are treated as service or warranty matters, not insurance losses. Insurance can step in if an external accident damages a component (for example, a bent rod causing a seal failure). -
What is the Kubota Orange Protection Program?
The Orange Protection Program is Kubota’s extended warranty that adds one or two extra years of coverage for eligible models beyond the standard limited warranty, including both basic and powertrain components. It offers no‑deductible, manufacturer‑administered coverage using genuine Kubota parts and is fully transferable. -
Can I buy extended warranty after I purchase my tractor?
Yes, Kubota states that Orange Protection can be purchased at any time before the original basic warranty expires, allowing owners to decide later if they want the extra protection. Many dealers will quote and add it during the purchase process, and financing is often available. -
Does Kubota insurance satisfy finance requirements?
For financed equipment, Kubota Credit typically requires proof of suitable physical damage insurance to protect its security interest, and KTAC’s term policies are structured to meet that requirement with locked‑in rates over the contract term. For contracts longer than 60 months, replacement‑cost benefits may apply only if a total loss occurs within the first 60 months. -
How is the insured value determined?
Kubota‑endorsed property damage plans generally insure the machine up to its original sales price, and some offer 100% sales price protection with replacement by new Kubota equipment of like kind and quality in total loss scenarios. This means you are not limited to depreciated “actual cash value” like many generic policies. -
Are attachments and implements covered?
Dealer‑level KTAC information often shows coverage extending to the listed equipment on the sales contract, including mounted implements and attachments, as long as they are part of the insured schedule. However, wear parts such as bucket teeth and cutting edges remain excluded under warranty and may be treated differently for insurance, so it is vital to list high‑value implements explicitly. -
Does Kubota insurance cover commercial use?
Kubota describes KTAC insurance as suitable for both personal and commercial users, with coverage tailored to typical Kubota applications across agriculture, landscaping and construction. Still, you must disclose intended commercial use to ensure the policy is correctly rated and valid. -
Can I cancel KTAC if I switch insurers?
Owners who refinance, pay off early or switch to another insurer can generally cancel KTAC by contacting the agency, though refund rules depend on the policy type and remaining term. It is important to maintain continuous equivalent coverage if your finance agreement still requires insurance. -
How do I file a Kubota insurance claim?
Claims are initiated by contacting KTAC or the listed insurer/agent, usually via a dedicated phone number or online form, and then providing details such as serial number, date of loss and description of damage. Dealers often help by supplying repair estimates and photographs so the adjuster can authorise work quickly. -
Does KTAC limit who can repair my equipment?
Kubota emphasises that repairs under its extended warranty are performed with genuine Kubota parts at authorised dealers, and the same dealer network is typically involved in insurance repairs. Using a Kubota dealer helps ensure parts availability and that structural or safety‑critical components are restored correctly. -
Is there any penalty for multiple claims?
Dealer brochures and marketing materials point out that there is no penalty for filing claims under KTAC insurance beyond paying the deductible, which encourages owners to use the coverage rather than “self‑insure” small accidents. However, as with any insurance, claim history can influence renewal terms in the longer term. -
Are rodent or insect infestations covered?
Kubota‑endorsed property damage coverage historically excluded infestation, but policy wording was updated so that KTAC removed “infestation” as an exclusion in 2018 and made that change retroactive for active policies. This means damage caused by pests during storage can potentially be covered, though you should confirm current terms. -
Does Kubota insurance cover giant, unusual or catastrophic events?
Policy exclusions list extreme scenarios such as nuclear accidents, war, terrorism and even tongue‑in‑cheek references to “giant monster attacks” as not covered, underlining that the focus is normal real‑world risks, not science‑fiction events. Everyday severe events like tornadoes, hurricanes, hail and earthquakes (where specified) are, however, among the standard covered perils. -
Where can I get more information or a quote?
Owners can obtain detailed terms and quotes through their local authorised Kubota dealer or directly from KTAC via its website or contact centre. Because coverages and eligibility vary by country and state, a local dealer or agent is the best source for precise, up‑to‑date details.
Kubota Insurance Cover explained
Kubota‑style “all‑risk” equipment insurance is designed to protect your tractor, mower or construction machine against the real‑world hazards you worry about most: theft, fire, collision, rollover, falling objects, hail, tornado, flood, vandalism and more.
This kind of policy focuses on accidental physical damage and loss to the machine itself, wherever you’re using it, rather than only when it’s parked at home.
Below is a long‑form post you can adapt for your site (targeting roughly 2,000–2,500 words) plus a 20+ question FAQ you can drop straight into WordPress.
What “all‑risk” Kubota equipment insurance means
When people talk about Kubota‑endorsed or tractor‑specific “all‑risk” insurance, they usually mean a policy that will respond to almost any sudden, accidental physical loss or damage unless it is clearly excluded in the wording.
Instead of listing only a few named perils, the policy assumes everything is covered by default, then carves out exceptions like wear and tear, mechanical failure, war and similar extremes.
For a tractor or compact machine owner, that’s useful because you don’t have to guess whether a particular mishap is on the list. A barn fire, a theft from a jobsite, a rollover on a slope, a tree falling on the cab, a hailstorm smashing the bonnet, floodwater filling the transmission – these are all typical “all‑risk” scenarios the insurer expects to see. The key is that the damage must be accidental, sudden, and external, not a slow internal failure.
Kubota Insurance – Why generic home or farm policies often fall short
Many owners assume their new Kubota or similar tractor is fully protected by their homeowners, farm or business policy. In practice, these generic policies often have narrow definitions and low sub‑limits for mobile agricultural or construction equipment. Common limitations include:
-
Cover only while the machine is “on premises” and not when you take it off‑site.
-
Excluding collision and rollover damage completely.
-
Treating the tractor as household contents with a low maximum payout.
-
Valuing losses on a depreciated “actual cash value” basis rather than replacement cost.
An all‑risk tractor policy is built the other way round. It expects your machine to be on the move, away from your yard, loading onto trailers, mowing steep banks and working in bad weather. That’s the whole point of owning it. The policy’s job is to respond to the common ways those activities can go wrong.
Kubota Insurance – Theft: protecting a highly desirable asset
Compact tractors, zero‑turn mowers and UTVs are prime targets for thieves because they’re easy to move and easy to resell. A theft‑inclusive all‑risk policy does two important things for you:
-
Pays to repair or replace your machine if it’s stolen or stripped for parts, typically after a short waiting period to see if police recover it.
-
Recognises theft risks not just at home but on jobsites, in fields, and while parked at customer premises.
Many owners underestimate how quickly a tractor can disappear from an outlying field or an unsecured barn. With the right insurance in place, that theft is a financial inconvenience rather than a catastrophe. You still lose time and productivity, but you don’t have to fund a new machine from scratch.
Kubota Insurance – Fire: barns, workshops and engine bays
Fire is another classic tractor risk. It might start in the engine bay due to debris build‑up on a hot exhaust, or in your barn, workshop, or even a neighbouring building. With all‑risk cover, it usually doesn’t matter where the fire starts – if the tractor is damaged by it, you have a claim.
Real‑world examples include:
-
A hay barn catching light and taking a tractor with it.
-
A wiring fault leading to an under‑hood fire.
-
A wildfire or field fire running through stored equipment.
In each of these, the tractor is an asset and the policy’s job is to get you back to an equivalent position: repaired or replaced, minus the deductible.
Kubota Insurance – Collision and rollover: real‑world working hazards
Collision and rollover are precisely the kinds of events that standard home policies dislike and specialist tractor policies are built to handle.
Collision
Collision simply means striking another object: a post, a tree, a parked vehicle, a wall, or even a trailer. On compact tractor forums you see endless stories of:
-
Buckets catching gateposts.
-
Mowers clipping stone walls.
-
Loaders nudging parked vehicles or equipment.
Under an all‑risk equipment policy, those impacts fall under “accidental physical damage.” If the collision bends the loader, damages the chassis or breaks the bonnet, you’re covered subject to the deductible and any valuation rules.
Rollover / upset
Rollover (also called “upset”) is a major design peril for tractor policies. Slopes, ditches, banks and soft ground all create tipping risk, especially with front loaders or heavy rear implements fitted. A rollover can:
-
Crush cabs, fenders and ROPS structures.
-
Damage axles, steering and hydraulics.
-
Lead to fluid loss and internal contamination.
An all‑risk tractor policy treats that physical damage as a covered event. Where people get confused is with any injuries or third‑party damage – those are liability issues, not property damage. You need separate liability cover to address those.
Kubota Insurance – Falling objects: trees, limbs and debris
Falling objects is the catch‑all for trees and branches in storms, building materials falling during construction, or even simple accidents like a loader bucket dropping unexpectedly. Because tractors often live under trees, work alongside buildings, or operate near other machinery, this is a surprisingly common peril.
An all‑risk policy that explicitly lists falling objects gives you peace of mind if a storm or operator error leads to something landing on the machine. Again, the key is that the damage is sudden and external – a tree falls and crushes the bonnet, for example – rather than a slow internal issue.
Kubota Insurance – Hail and tornado: severe weather on open ground
Agricultural and rural owners are highly exposed to severe weather. Tractors often live in open yards, are used in fields far from shelter, and can’t always be rushed indoors when the forecast turns.
-
Hail can dent bonnets, roofs and panels, shatter lights and windscreens, and damage cabs.
-
Tornadoes and severe windstorms can flip machines, hurl debris, collapse sheds and throw trees onto vehicles.
With hail and tornado listed as covered perils, you avoid arguments over whether “cosmetic” damage matters. In practice, hail and wind damage can hurt resale value and, in bad cases, impair structural strength. An all‑risk policy is designed to treat that as a genuine loss.
Kubota Insurance – Flood: high‑risk, often excluded elsewhere
Flood is one of the big dividing lines between robust all‑risk equipment policies and many basic home or farm policies. Water ingress can:
-
Destroy engines and transmissions.
-
Contaminate hydraulic systems.
-
Damage electrical systems and control modules.
If your tractor lives near a river, on low ground or in a flood‑prone region, having flood explicitly included is critical. Without it, a single incident can write off the machine with no payout.
With it, the insurer treats the flood as any other accidental event and responds according to your policy’s valuation rules.
Kubota Insurance – Vandalism and malicious damage
Finally, vandalism and malicious damage are important to cover because they’re unpredictable and often targeted. Broken glass, slashed seats, damaged wiring harnesses, sugar in fuel tanks – rural vandalism can be nasty and expensive to fix.
An all‑risk tractor policy that includes vandalism recognizes that you can’t control every person who walks past your property or job site. As long as you take reasonable precautions (locking, sensible storage), the policy is there to make you whole if someone intentionally damages your machine.
Kubota Insurance – What all‑risk tractor insurance does not cover
Despite the broad list of perils, there are always exclusions. Owners often confuse these policies with warranties or maintenance plans, which leads to frustration. Typical exclusions include:
-
Normal wear and tear – Tyre wear, blade dulling, worn bushings, faded paint.
-
Mechanical or electrical breakdown without an external cause – A pump failing internally, a ECU dying on its own, seals wearing out.
-
Poor maintenance or abuse – Running without oil, ignoring coolant leaks, obvious overloading and misuse.
-
Non‑accidental loss – Gradual rust, slow corrosion, long‑term deterioration.
-
Extreme events like war or nuclear incidents – Standard exclusions in almost all property policies.
Think of all‑risk tractor insurance as protection against the outside world, not against the machine simply ageing.
For internal failures and manufacturing defects, manufacturer warranty or extended warranty programs (like Orange Protection) are the appropriate product, not property insurance.
Kubota Insurance – How claims typically work
Although processes vary between providers, a typical claim flow looks like this:
-
Incident occurs – Theft, fire, rollover, collision, storm, etc.
-
Secure the site – Ensure people are safe, switch off power, stabilise the machine if possible.
-
Notify the insurer promptly – Provide date, time, location, brief description and any police report numbers for theft or vandalism.
-
Document the damage – Take photos or video of the scene and the machine from multiple angles.
-
Dealer estimate – Your dealer inspects the machine, lists the parts and labour needed, and sends an estimate and photos to the insurer.
-
Adjuster review and approval – The insurer reviews coverage, may ask questions, and then approves repair or total‑loss settlement.
-
Repair or replacement – Repairs proceed at an agreed shop, or the insurer arranges settlement if the machine is written off.
The smoother the relationship between your insurer and your dealer, the less painful this process is. That’s why brand‑aligned products are popular: the insurer sees the same machines and the same kinds of claims every day.
Practical tips for owners
To get the most out of an all‑risk tractor policy:
-
List high‑value attachments – Make sure loaders, backhoes and specialist implements are clearly included where required.
-
Keep good records – Store invoices, serial numbers, photos and maintenance records where you can access them quickly.
-
Follow basic security – Locked barns, immobilisers, trailered machines parked sensibly; insurers expect reasonable precautions.
-
Stick to maintenance schedules – Poor maintenance is a common reason to reduce or deny payouts where it clearly contributed to the loss.
-
Review limits and deductibles annually – As values and parts prices change, make sure your sum insured and excess still make sense.
Kubota Insurance FAQ: All‑Risk Tractor Insurance
You can paste this straight into your post and format each as its own block or use FAQ schema.
1. What does “all‑risk” tractor insurance actually mean?
“All‑risk” means the policy covers any sudden, accidental physical loss or damage to your tractor unless it is specifically excluded in the wording. Rather than listing just a few perils, it assumes everything is covered by default and then carves out exceptions.
2. Which perils are usually included?
A good tractor all‑risk policy typically includes theft, fire, collision, rollover (upset), falling objects (like trees or debris), hail, tornado and other windstorms, flood, vandalism and many other accidental events. Always check your own policy schedule to confirm.
3. Is theft covered if my tractor is stolen from a job site?
Yes, provided your policy includes theft and does not limit cover only to your home premises. Most specialist tractor policies follow the machine on and off your property, including jobsites and customer locations.
4. How does fire coverage work for tractors?
If your tractor is damaged by fire – whether the fire starts in the engine bay, the building it’s stored in, or comes from an external source like a wildfire – the policy treats that as a covered loss, subject to your deductible and any valuation rules.
5. What counts as a “collision” claim?
Collision generally means your tractor strikes another object: a vehicle, wall, tree, post, fence, or similar. If that impact causes physical damage to the machine, it’s usually covered under an all‑risk equipment policy.
6. Is rollover or tip‑over really covered?
Yes, rollover (sometimes called “upset”) is specifically recognised as a major peril for tractors. If the machine tips on a slope or into a ditch and suffers damage, that is normally a covered event. Injuries or damage to others remain a separate liability issue.
7. Are falling trees or branches covered?
Yes. Falling objects is a standard peril in most tractor all‑risk policies. If a tree or heavy limb drops onto the machine and damages the cab, bonnet or structure, that is typically a valid claim.
8. How does hail damage coverage work?
Hail can dent panels, damage roofs, break glass and destroy lights. With hail listed as a covered peril, those repairs or replacements are handled under the policy, even if the damage is mostly cosmetic but affects value and function.
9. Is tornado or severe windstorm damage covered?
If your policy includes windstorm or tornado, damage from these events is covered: machines flipped by wind, sheds collapsing on tractors, or debris striking the machine. Flooding caused by those storms may also be covered where flood is included.
10. Does the policy cover flood damage to my tractor?
Not all policies do, so you must check. Where flood is explicitly included, water damage to engines, transmissions, hydraulics and electrics from river overflow or surface flooding is treated as a covered loss. Without flood cover, the same incident might not be insured at all.
11. Is vandalism or malicious damage included?
Yes, vandalism is commonly listed as a covered peril. Broken glass, damaged wiring, deliberate damage to panels or controls – all of these fall under malicious damage and are usually covered if you’ve taken reasonable security precautions.
12. Does all‑risk cover mechanical breakdown or wear and tear?
No. All‑risk refers to external events. Mechanical or electrical breakdowns, normal wear, and gradual deterioration are excluded. Those issues are either your maintenance responsibility or, if related to defects, a warranty/extended warranty matter.
13. What about damage caused by poor maintenance?
If poor maintenance clearly contributes to the loss – for example, running with no oil until the engine seizes – insurers can reduce or deny the claim. You’re expected to maintain the machine according to the manufacturer’s schedule.
14. Is there usually a deductible (excess) on tractor claims?
Yes. Most policies have a fixed deductible that you pay toward each claim. It’s often set at a level that makes serious losses affordable but discourages very small nuisance claims. Check your policy for the exact amount.
15. Are attachments and implements covered too?
Often they are, especially if listed on the sales invoice or the policy schedule (loaders, backhoes, mower decks, etc.). However, wear parts like blades and bucket teeth may be treated differently, so it’s important to ensure expensive implements are clearly specified.
16. Does the policy cover my tractor off‑road and off my property?
One of the main advantages of a specialist tractor policy is that it’s designed to follow the machine wherever it’s legitimately working: on your land, at a neighbour’s, on a job site, or on a trailer to the dealer. Many simple homeowners policies do not offer that level of portability.
17. Is liability for injuries or damage to others included?
Usually not. The all‑risk policy is about your machine’s physical damage. Liability for injuries to other people or their property is a separate policy or section (public, farm or commercial liability). You need both types of cover for full protection.
18. How is the payout calculated if my tractor is written off?
Policies differ, but many aim for replacement‑cost style settlement in the early years, based on the original purchase price, possibly including taxes and certain fees. Others use actual cash value with depreciation. Check your documentation so you know whether you’d be put into a comparable new/used machine or receive a depreciated cheque.
19. What should I do immediately after a loss?
Prioritise safety, then: secure the scene, take photos or video, note dates and times, and notify your insurer quickly. For theft or vandalism, file a police report. Contact your dealer for an assessment and estimate – they often help coordinate with the insurer.
20. Can I choose my own repairer?
This depends on the insurer. Many are happy to work through authorised dealers because they trust their expertise and parts sourcing. If you want to use an independent shop, you must confirm that the insurer agrees and that labour rates and parts are acceptable under the policy.
21. Is this kind of cover worth the cost?
For new or high‑value tractors, and for machines that are essential to your business, a broad all‑risk policy is often excellent value. One theft, flood, rollover or fire can cost more than years of premium. For older, low‑value or lightly‑used machines, some owners choose to self‑insure and keep a repair/replacement fund instead.
Kubota Insurance Claims Process
Kubota‑branded insurance and warranty products are designed to run through the dealer network, and that really shapes how the claims process works. In most cases, you don’t negotiate directly with an adjuster on your own; you work with your Kubota dealer, and they coordinate with Kubota or the insurance administrator for approval.
Kubota Insurance & Warranty Claims Process: How It Really Works
When you buy a Kubota tractor or implement, you’re not just buying a machine – you’re buying into a support system of warranty, extended warranty and sometimes Kubota‑endorsed insurance. That support system becomes crucial the day something goes wrong.
For owners, the key question is simple: what actually happens when I have to make a claim?
This guide walks through:
-
How Kubota warranty and extended warranty claims work via your dealer
-
How Kubota‑endorsed insurance style claims (physical damage) are typically handled
-
The difference between OEM (Kubota) approval and third‑party authorisation
-
Practical tips to make claims faster, smoother and more successful
You can adapt the details to your specific region (for example, KTAC in the US, or dealer‑arranged tractor insurance in the UK/EU).
Two different “claims” worlds: warranty vs insurance
Before diving into steps, you need to separate two completely different types of claim:
-
Warranty / Extended Warranty (e.g. Orange Protection)
-
Covers defects in materials or workmanship.
-
Claims are handled as warranty jobs through Kubota’s own system.
-
The decision maker is Kubota (the manufacturer), not an outside insurance company.
-
-
Insurance / Physical Damage (e.g. Kubota‑endorsed tractor insurance)
-
Covers accidental physical damage and loss from external events like theft, fire, collision, rollover, flood and vandalism.
-
Claims are handled as insurance claims.
-
The decision maker is an insurance provider (sometimes a Kubota‑aligned agency, sometimes a separate insurer).
-
In both cases, your Kubota dealer is at the centre. But the back‑end approval process is different, and you’ll notice that in how decisions are made and who pays the bill.
Kubota Insurance – The Kubota warranty claim process: step by step
When something fails that looks like a defect rather than an accident, you’re in warranty territory. That might be a leaking hydraulic valve, a faulty ECU, a transmission issue or a cracked casting with no impact history.
Here’s how a typical Kubota warranty or Orange Protection claim plays out from the owner’s perspective.
1. You notice a problem
You might see:
-
Warning lights, error codes or derated power.
-
Fluid leaks with no sign of external damage.
-
A driveline noise, failure to engage, or loss of hydraulic function.
-
A part physically cracking or breaking under normal use.
Your first step is to stop using the machine if continued operation might make things worse, and note the hours on the meter and what you were doing when the fault appeared.
2. Contact your Kubota dealer
Next, you call or email your nearest authorised Kubota dealer. Provide:
-
Model and serial number.
-
Current hours.
-
A clear description of the fault and when it started.
-
Any photos or video that show visible issues.
The dealer will check your warranty status (original warranty end date and, if relevant, extended warranty like Orange Protection).
3. Dealer diagnosis
You bring the tractor in (or they collect it), or a technician visits on‑site. The dealer:
-
Performs diagnostic tests and inspections.
-
Determines likely cause: defect vs damage vs wear.
-
Estimates parts and labour required.
This stage is crucial. If the dealer can show that the issue is clearly a defect (and not a result of abuse or neglect), their job of convincing Kubota is much easier.
4. Dealer submits a warranty claim
The dealer then submits a warranty claim to Kubota. That claim includes:
-
Details of the machine (model, serial, hours).
-
Description of the fault and context (what the machine was doing).
-
Photos, test reports and technician notes.
-
A list of parts and labour hours required for the repair.
From your point of view, you are not negotiating directly with Kubota – the dealer acts as your technical advocate.
5. Kubota reviews and approves (or queries)
Kubota’s warranty team reviews the claim. They might:
-
Approve it straightforwardly if it’s clearly a covered defect.
-
Ask for more information (extra photos, further diagnostics, oil samples).
-
Reject some items if they see them as wear‑and‑tear or unrelated damage.
This is where good documentation and honest, clear reporting matter. If the failure is borderline (for example, a component damaged in a minor collision), Kubota might push back and treat it as non‑warranty damage.
6. Repair and completion
Once approved, the dealer proceeds with the repair:
-
Genuine Kubota parts are ordered and fitted.
-
Labour is billed to Kubota under warranty rates, not to you.
-
You may pay only for non‑covered extras (like fluids or filters not part of the specific repair, or any optional upgrades you choose at the same time).
If you have Orange Protection, this process is identical – the extended warranty works exactly like the original warranty, just in later years and higher hours.
From your perspective, the claim process is: “I take it to the dealer, they fix it and Kubota pays.”
The Kubota‑endorsed insurance claim process: step by step
Now let’s switch to insurance/physical damage – things like theft, fire, rollover, collision, flood and vandalism. The claim process has similar stages but a different decision maker.
1. Incident and immediate actions
A typical insured event might be:
-
Tractor stolen from a shed or jobsite.
-
Machine rolled over on a bank.
-
Barn fire damaging multiple pieces of equipment.
-
Floodwater entering the shed and submerging the tractor.
-
Vandalism: broken glass, slashed wiring, malicious damage.
Immediately after the incident:
-
Make sure everyone is safe; call emergency services if needed.
-
For theft or vandalism, contact the police and get a crime/incident number.
-
For fire, get a fire report if one is created.
-
Take photos/video of the scene and damage before moving anything, if it’s safe to do so.
2. Notify your insurance provider
If you have a Kubota‑endorsed policy (or any specialist tractor insurance), you then notify the insurer. You’ll need:
-
Policy number.
-
Date, time and location of the incident.
-
Basic description of what happened.
-
Crime/FIRE report numbers where applicable.
They may give immediate guidance on what to do with the tractor (e.g. move it somewhere secure, don’t attempt to start it after flood, etc.).
3. Contact your Kubota dealer
Next, you call your Kubota dealer to start the technical side:
-
Explain that you have had an insured loss.
-
Ask them to inspect the machine and prepare a repair estimate.
-
Provide your insurance claim reference so the dealer can liaise directly with the insurer if needed.
Often, the dealer knows the insurer’s procedures very well, particularly when the policy is Kubota‑endorsed – they deal with similar claims regularly.
4. Dealer inspection and estimate
The dealer assesses the damage:
-
Visual inspection and photos.
-
Diagnostic tests to see what’s internally damaged (important for fires and flood).
-
A line‑by‑line estimate: parts, labour, and any recommended replacements (for example, replacing all fluids after water contamination).
They send this estimate to the insurer, sometimes directly, sometimes via you.
5. Insurance adjuster review
The insurer’s claims handler or adjuster reviews the estimate and the circumstances:
-
Confirm that the cause of loss is a covered peril under your policy.
-
Check that the extent of repairs is reasonable and necessary.
-
Decide whether to repair or declare a total loss (write‑off).
If necessary, an independent field adjuster may visit to inspect the tractor and reconcile any differences between the dealer’s estimate and the insurer’s view.
6. Authorisation and excess
Once satisfied, the insurer issues authorisation to the dealer:
-
“Go ahead and repair” – up to an approved amount.
-
Or “Total loss” – they’ll calculate a payout based on the policy’s valuation rules.
You’ll be told:
-
That the claim is approved.
-
What your deductible/excess is.
-
Any specific conditions (for example, which parts are being replaced vs repaired).
The dealer will either collect the deductible from you or the insurer will deduct it from the settlement total.
7. Repair or replacement
If the machine is repairable:
-
The dealer carries out the work.
-
They invoice the insurer (less any deductible you pay).
If it’s a total loss:
-
The insurer may pay off any finance outstanding first (if the tractor is financed).
-
Any balance, within policy limits, is paid to you (or towards a replacement machine, depending on arrangements).
Your role is mainly providing information, signing forms, and paying the deductible – the heavy lifting is between the dealer and insurer.
Kubota Insurance : OEM approval vs third‑party authorisation
This is where the snippet you quoted comes in:
*“Claim process: Same as standard Kubota warranty claim, via dealer; Kubota approves.
You or dealer must get pre‑authorisation from the warranty company; more variability.”*
This captures the key practical difference:
-
With Kubota‑run warranty/extended warranty, the dealer is talking to Kubota, who knows the machines inside‑out and follows consistent internal warranty rules.
-
With third‑party warranties or insurance, the dealer (or you) must get approval from an external company that has its own rules, priorities and thresholds.
That can mean:
-
More documentation requirements.
-
Stricter interpretations of “wear vs failure.”
-
Pressure to use cheaper parts or less labour if the contract caps costs.
It doesn’t automatically mean third‑party is bad, but it does mean more variability compared to the very predictable “Kubota approves” path.
Common sticking points in Kubota Insurance claims
Whether it’s warranty or insurance, there are a few recurring friction points that owners run into.
1. Grey area between defect and damage
Example:
A hydraulic cylinder rod bends slightly in use, later causing seal failure and leaks.
-
Kubota warranty may view the bent rod as damage from a hard impact, not a defect.
-
Insurance may treat the impact as an insured event (if it can be linked to a covered peril).
Clear photos and a consistent story help clarify which side of the fence a claim belongs on.
2. Missing maintenance records
If an engine or drivetrain fails and the manufacturer/insurer believes poor maintenance contributed, they may:
-
Reduce the payout.
-
Or refuse the claim altogether.
Keeping basic records (dealer invoices, DIY service logs, dated photos of hour meter at service) makes it much easier to prove you’ve maintained the machine properly.
3. Modifications and non‑OEM parts
Big modifications (tuning, non‑OEM loader systems, homemade attachments) can create headaches:
-
Kubota warranty may not cover failures linked to unauthorised modifications.
-
Insurers may ask whether modifications were disclosed when the policy was written.
If you make major changes, it’s wise to tell both your dealer and your insurer.
How to make Kubota claims faster and smoother
For your blog, you can wrap this into a practical checklist:
-
Call your dealer first for technical failures
If a component fails without any obvious accident, treat it as a potential warranty issue and go straight to the dealer. Don’t assume you have to handle everything yourself – the dealer’s processes are designed to run warranty claims smoothly. -
Call your insurer first for obvious damage events
If you’ve had a theft, fire, rollover, collision or flood, notify insurance promptly, then loop in the dealer for assessment and repairs. -
Have your key info ready
Always have to hand:-
Model and serial number
-
Hours on the machine
-
Policy number (for insurance)
-
Warranty documentation or original purchase date
-
-
Document everything
Take plenty of photos from multiple angles. If it’s a technical issue, capture fault codes or dash lights. For accidents, show the environment and anything that caused the damage. -
Be honest and consistent
Don’t try to “massage” the story to fit warranty or insurance; inconsistencies are what trigger extra scrutiny. A clear, accurate timeline is much more convincing. -
Stay in contact with your dealer
Check in periodically. Dealers are often busy, but polite follow‑ups keep your claim on their radar and help you understand where you are in the approval chain.
Example claim stories
-
Warranty case: HST failure at 1,200 hours
The machine loses drive with no external damage. Dealer diagnoses internal failure, submits a warranty claim with photos and oil analysis results. Kubota approves as a manufacturing defect, repair is completed under warranty, owner pays nothing. -
Insurance case: Tractor rollover into a ditch
Owner misjudges a bank, tractor slides and rolls. ROPS and cab are damaged but the operator is unhurt. Insurance is notified, dealer estimates repairs, insurer approves as a rollover claim. Owner pays a fixed deductible, the rest of the repair bill is covered.
Conclusion: use the dealer as your hub
The big takeaway for Kubota owners is that the dealer is your claims hub:
-
For Kubota warranty and Orange Protection, the process is essentially: “Same as standard Kubota warranty claim, via dealer; Kubota approves.”
-
For Kubota‑endorsed insurance or third‑party policies, the process becomes: “Dealer and/or owner must get pre‑authorisation from the warranty or insurance company; more variability.”
Understanding that split lets you route problems correctly from day one, shorten downtime, and avoid going in circles between different companies.